Retirees and other income investors are finally getting a chance to buy some top TSX dividend stocks at discounted prices for their self-directed Tax-Free Savings Account (TFSA) portfolios.
Source: Getty Images
Enbridge share price
Enbridge (TSX: ENB) trades near $66.50 per share at the time of writing, compared to $80 earlier this year. The pullback over the past few months has pushed the dividend yield up to an attractive 5.8%.
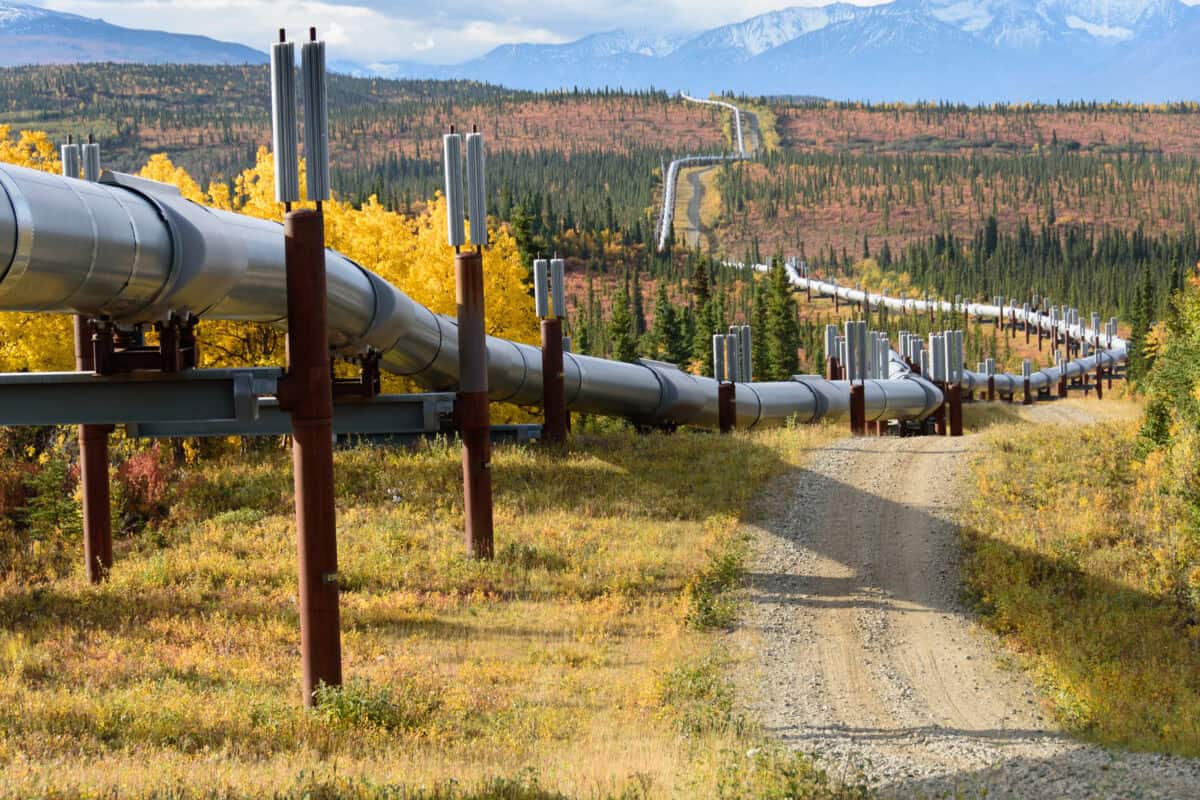
Enbridge is a major player in the North American energy infrastructure industry, as its assets are strategically important for the smooth operation of both the Canadian and American economies. Enbridge’s oil pipelines move about 30% of the oil produced in the two countries. The natural gas transmission pipelines carry roughly 20% of the natural gas used in the United States.
Enbridge’s acquisitions over the past five years have largely focused on diversifying the asset portfolio beyond pipeline infrastructure. Management acquired an oil export terminal in Texas for US$3 billion, and Enbridge is a partner on the Woodfibre liquefied natural gas (LNG) export facility nearing completion on the coast of British Columbia. Enbridge also expanded its utilities operations with a US$14 billion deal in 2024 to buy three natural gas distribution utilities in the United States. In addition, Enbridge acquired the third-largest American solar and wind project developer. Recent transactions worth more than US$3 billion, however, have focused once again on oil infrastructure in the United States.
On the development side, Enbridge is working through a $41 billion secured capital program with roughly $10 billion per year in new assets being put into operation over the medium term. The boost to cash flow from the acquisitions and development projects is expected to be about 5% annually. This should enable Enbridge to continue raising its dividend. The board has increased the distribution for 31 consecutive years.
Looking ahead, the outlook should be positive for the company with respect to energy demand. New gas-fired power generation facilities are being built to provide electricity to AI data centres. At the same time, global demand for Canadian and American oil and natural gas is on the rise as countries look for reliable supplies from stable producers after the shocks to the market that have occurred due to the wars in Ukraine and Iran.
Higher oil and natural gas volumes across the transmission, storage, export, and utility businesses should support revenue growth.
Risks
Enbridge uses debt to fund part of its growth program, so rising borrowing costs can be problematic. In recent months, concerns about inflation have driven a surge in expectations for rate hikes by the central banks. This has contributed to the rise in bond yields. The U.S. Federal Reserve already raised interest rates once, and more hikes are expected in the coming months. Canada will likely follow the US with its own rate increases.
If oil prices remain too high for too long the result could be more aggressive inflation across the broader economy. This would force the central banks to raise rates by large amounts or at a faster pace. Concerns about higher rates are the main reason Enbridge’s share price has pulled back from the 2026 highs. Further downside could be on the way if inflation spikes.
The bottom line
Near-term turbulence is expected in the market, but Enbridge’s dividend should continue to grow, and the current yield is attractive for income investors. Additional downside would be viewed as an opportunity to increase the position. If you have some cash to put to work, this stock deserves to be on your radar.
